From Al Capone To Mickey Cohen: How Tax Crimes Helped Define Alcatraz
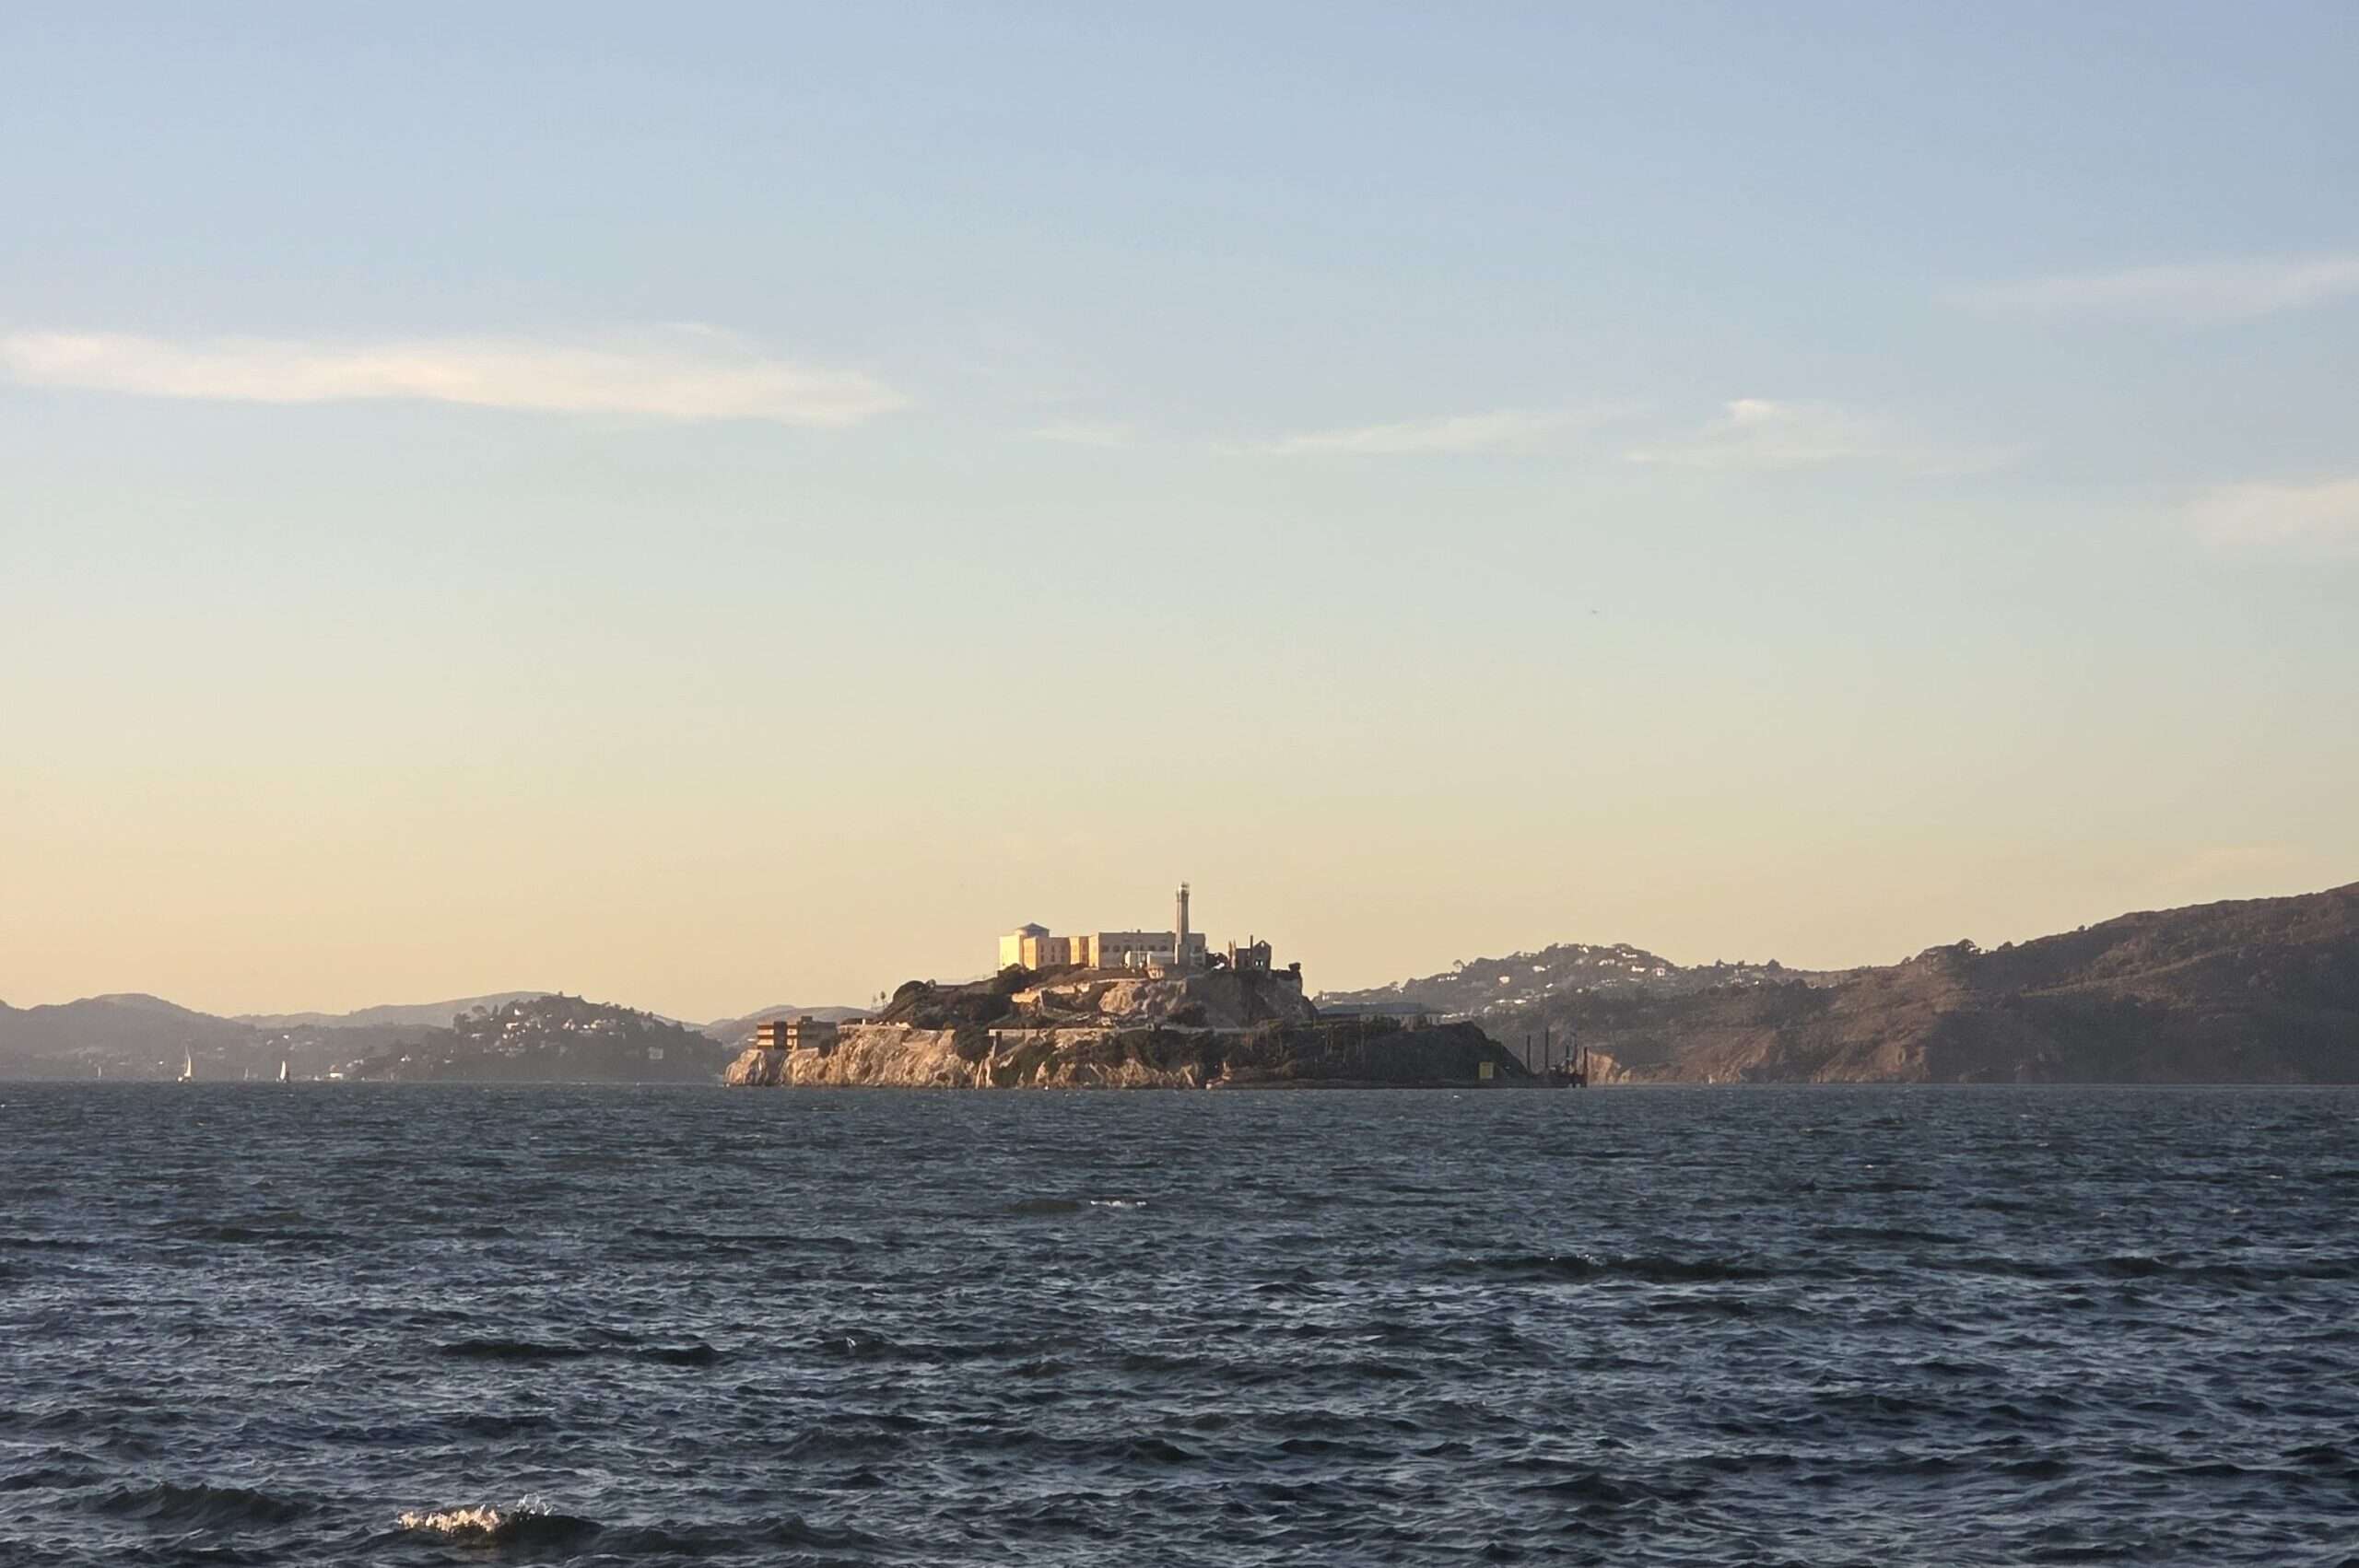
From the shore of San Francisco (where I’m currently speaking at a conference), Alcatraz looks almost peaceful. The island sits in the middle of the bay, surrounded by cold water, with the city skyline in the distance.
Today, it’s one of the city’s most popular tourist attractions, as I well know, having sought it out this week while I’m here. Unfortunately for me, it’s currently closed for repairs, but most of the time, you can ferry over and check it out—it’s a now a national park. But for nearly three decades, it was home to some of America’s most notorious criminals. Among them were bank robbers, kidnappers, murderers, and organized crime figures. And at least two of its most famous residents were there because of federal income tax convictions.
I was, of course, familiar with Al Capone’s stay at The Rock. Being here inspired me to do a little digging, and I learned about Mickey Cohen, too. Both Capone and Cohen were notorious for their involvement in organized crime, but it was the tax laws that helped put them behind bars. Their stories also provide an interesting set of bookends for Alcatraz. Capone arrived in 1934, just weeks after the island opened as a federal penitentiary. Cohen left in 1963, just before it closed.
While their criminal careers were separated by decades, their cases shared a common thread: The federal government used the tax laws to prosecute men whose other alleged criminal activities had proved far more difficult to bring into court.
Al Capone: The Gangster Who Couldn’t Escape the Taxman
“They can’t collect legal taxes from illegal money.” Or so Al Capone reportedly claimed. Spoiler alert: he was wrong.
By the time Capone went on trial in 1931, he was among America’s most recognizable criminals. The Chicago mob boss had made a fortune during Prohibition, when illegal liquor operations, gambling, and other rackets generated enormous sums.
Capone took control of much of Chicago’s organized crime in 1925, after his mentor, Johnny Torrio, survived an assassination attempt and retired from the mob business. Over the next several years, Capone expanded those operations, building an empire worth millions and becoming one of the country’s most notorious gangsters.
As Capone’s empire grew, so did the violence. Capone was widely suspected of ordering the infamous St. Valentine’s Day Massacre in February 1929, when seven members or associates of a rival gang were gunned down. Conveniently, Capone was in Florida at the time. He was never prosecuted for the murders, and federal authorities continued to struggle to build cases against him for other violent crimes. But another development, far removed from the violence in Chicago, would ultimately help bring him down.
The Supreme Court Says Illegal Income Is Taxable
On May 16, 1927, the U.S. Supreme Court decided United States v. Sullivan, 274 U.S. 259 (1927). The case involved a bootlegger who argued that he could not be required to file an income tax return because doing so would compel him to disclose criminal activity, violating his Fifth Amendment right against self-incrimination.
The Supreme Court disagreed. Writing for the Court, Justice Oliver Wendell Holmes made clear that income from illegal liquor sales was subject to federal income tax. While taxpayers could assert the Fifth Amendment privilege against particular disclosures, they could not simply refuse to file a return on that basis. The decision was important for federal tax enforcement because it confirmed that illegal profits were taxable, even when the underlying business violated federal law.
Following Capone’s Money
By the late 1920s, federal authorities had grown frustrated by their inability to successfully prosecute Capone for his alleged criminal activities. The Treasury Department summoned Elmer Irey, the first chief of the IRS Intelligence Unit (now IRS Criminal Investigation, or IRS-CI), and told him to simply “get Capone.” Irey is said to have replied, “We’ll get right on it.” With that, Special Agent Frank Wilson and other Treasury investigators began tracing the mob boss’s financial activities.
It was not easy. Capone operated largely in cash, avoided keeping financial records in his own name, and had never filed a federal income tax return. Yet there was plenty of evidence that he was spending money. So, investigators used financial records, witness testimony, and other evidence to reconstruct the income Capone had received but never reported.
In June 1931, Capone was indicted on 22 counts involving federal income tax evasion and failure to file returns. He initially agreed to plead guilty to federal tax and Prohibition-related charges, apparently believing the arrangement would result in a prison sentence of about two and a half years. But the judge made clear he was not bound by the proposed agreement. Capone withdrew his guilty plea, and the tax case proceeded to trial.
On October 17, 1931, the jury convicted Capone on three felony counts of attempting to evade federal income taxes for 1925, 1926, and 1927, along with two misdemeanor counts of failing to file income tax returns for 1928 and 1929. One week later, he was sentenced to 11 years in prison, fined $50,000, and ordered to pay court costs. He also owed more than $215,000 in back taxes, plus interest.
Capone Goes To Alcatraz
Capone began serving his federal sentence at the Atlanta penitentiary in 1932. Reports suggested he enjoyed privileges there that ordinary inmates did not, much as he had during an earlier incarceration at Eastern State Penitentiary in Philadelphia.
That changed on August 22, 1934, when Capone was transferred to Alcatraz. According to one account, when Capone arrived, Warden James A. Johnston asked his name. Capone allegedly replied, “You know who I am.” Johnston’s response was less accommodating: “Here you are now known as AZ-85.”
The island had opened as a federal penitentiary earlier that month. It was intended to house prisoners federal officials considered particularly difficult to manage, with strict discipline and few privileges. Capone spent his days doing prison work, including laundry, and had little of the influence that had defined his life in Chicago. He reportedly acknowledged the change in his circumstances, telling the warden that Alcatraz had finally gotten the better of him.
But prison conditions were only part of Capone’s difficulties. His health deteriorated significantly while he was incarcerated. He had contracted syphilis years earlier, and the disease progressed, eventually causing serious neurological problems.
On January 6, 1939, after approximately four years and four months on the island, Capone was transferred out of Alcatraz to the federal prison at Terminal Island, near Los Angeles, and later to Lewisburg, Pennsylvania, where he was released in November 1939. He eventually returned to Florida, where he died on January 25, 1947, at age 48.
More than two decades after Capone’s arrival, another famous organized crime figure would cross San Francisco Bay.
Mickey Cohen: Another Tax Gangster, Years Later
Mickey Cohen was a different kind of gangster. While Capone’s criminal career was closely associated with Prohibition-era Chicago, Cohen became a prominent figure in Los Angeles organized crime, where his activities included gambling operations and connections to Hollywood. He was also unusually comfortable with publicity. Cohen cultivated relationships with celebrities, politicians, and reporters, becoming a recognizable public figure far beyond the criminal underworld.
Like Capone, however, Cohen attracted the attention of federal tax investigators. In 1951, Cohen was convicted of attempting to evade federal income taxes for 1946, 1947, and 1948. He was sentenced to five years in prison and fined $10,000, ultimately serving approximately four years before being paroled in October 1955.
After his release, federal authorities continued to pursue Cohen for unpaid taxes. Cohen maintained that money he received came from loans or gifts from friends, but prosecutors alleged that he was also taking steps to keep the government from collecting taxes he already owed.
In 1961, Cohen was convicted again, this time on eight federal counts involving false and fraudulent income tax returns for 1957 and 1958, attempts to evade payment of previously assessed taxes, concealment of property subject to a federal tax levy, and making a false statement to a Treasury agent. He received a 15-year prison sentence and $30,000 in fines.
On July 28, 1961, Cohen arrived at Alcatraz as inmate number 1518. His stay was interrupted that October when he was released on a $100,000 appeal bond. Cohen has been called the only prisoner ever bailed out of Alcatraz. However, the Ninth Circuit upheld his conviction, and the Supreme Court declined to hear his case. Cohen was returned to federal custody in May 1962 and back on Alcatraz by May 14.
Prison records describe Cohen as a cooperative inmate who kept a neat cell and worked in the clothing room. Whatever reputation he had outside prison, his institutional record was comparatively uneventful during his time on the island.
As Alcatraz prepared to close, prison officials began transferring inmates to other federal facilities. On February 26, 1963, Cohen was transferred to the federal penitentiary in Atlanta, just weeks before Alcatraz closed for good. He remained in the federal prison system until 1972 and died in 1976.
Why Tax Crimes Mattered
The cases against Capone and Cohen weren’t identical. In fact, the differences show the reach of federal tax enforcement.
Capone’s prosecution centered on unreported income from illegal operations. Investigators had to show he received taxable income and willfully tried to evade the taxes owed on it. Cohen’s later prosecution illustrates another side of the law—not only failing to report income, but also attempting to avoid paying taxes that have already been assessed. Both cases reflect an approach that has remained significant in federal criminal investigations.
When it comes to prosecuting organized criminals, witnesses may be reluctant to testify, and it may be difficult to link a particular defendant to a specific offense. But financial activity can leave its own evidence. Income, expenditures, records, assets, and efforts to conceal money can help investigators reconstruct transactions and establish tax violations, even when proving other criminal activity is difficult. As Capone and Cohen learned, tax laws can reach conduct that might otherwise be difficult to prosecute.
Alcatraz’ Legacy
Alcatraz closed as a federal penitentiary on March 21, 1963, after less than 30 years of operation. Its isolation, which had made it an ideal high-security prison, also made it extraordinarily expensive to maintain. By then, the island had become one of the most recognizable symbols of federal imprisonment in America.
Today, visitors come for the history, the famous prisoners, and the stories of escape attempts. Capone remains one of the names most closely associated with Alcatraz, while Cohen’s connection to the island is less familiar. But their stories belong together. Capone arrived near the beginning of the prison’s federal history and Cohen departed just before its end. Between them were decades of shifting criminal enterprises, evolving federal investigations, and a growing recognition that financial records could sometimes accomplish what more conventional criminal investigations could not.
The men may have been famous for their criminal reputations, but tax laws helped put them on the Rock. Their stories remind us that sometimes the most powerful weapon against organized crime isn’t a gun, it’s a tax return.



Want more Taxgirl?
Get tax news, explainers, deadlines, and more delivered straight to your inbox.
Subscribe →