Draft 2026 Form 1040 Adds New Citizenship And Work Authorization Question
The 2026 Form 1040 looks a little different this year—at least an early version does. A draft Form 1040 released on September 17 adds a new immigration-related question asking taxpayers whether they are U.S. citizens, U.S. nationals, or otherwise lawfully authorized to work in the United States.
The draft Form 1040 also relocates an existing line concerning a nonresident or dual-status spouse. The line previously appeared on the 2025 Form 1040 under Filing Status.
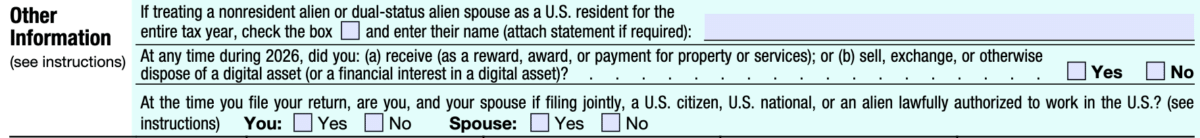
The changes appear in a new “Other Information” section near the top of the return’s front page. That box was labeled “Digital Assets” on the 2025 form since it only displayed the digital assets question, which first moved onto the front page of Form 1040 for the 2020 tax year after initially appearing on Schedule 1 in 2019. The 2026 draft turns that prime location into a spot for more compliance-focused questions.
A New Location For An Existing Tax Election
The first line reads:
If treating a nonresident alien or dual-status alien spouse as a U.S. resident for the entire tax year, check the box and enter their name (attach statement if required).
This isn’t a new concept. Under longstanding tax rules, a married couple may, in certain circumstances, elect to treat a nonresident alien spouse as a U.S. resident for federal income tax purposes. A similar election is available in some cases for a dual-status spouse. When the election applies, the spouses are generally treated as U.S. residents for income tax purposes for the relevant year, must report worldwide income, and, for the year of the election, generally file a joint return.
That distinction is important because U.S. tax residency is not the same as citizenship or immigration status. A person may be a resident alien for federal income tax purposes if they satisfy the green card test or the substantial presence test, and a person may be a dual-status individual if their federal tax residency changes during the year. The IRS itself notes that tax residency can differ from residency under immigration law or a tax treaty.
Checking the spouse box does not mean someone has become a U.S. citizen or obtained permission to work here. It concerns how that spouse is treated for federal income tax purposes.
The 2025 Form 1040 included this election directly in the Filing Status section, where taxpayers could check a box, enter the spouse’s name, and, if required, attach a statement. Now, the line has been moved out of Filing Status and into the new “Other Information” section.
The Citizenship Question Is Different
The draft Form 1040 also asks:
At the time you file your return, are you, and your spouse if filing jointly, a U.S. citizen, U.S. national, or an alien lawfully authorized to work in the U.S.? The taxpayer and spouse each have separate “Yes” and “No” boxes.
That question is more notable because it directly asks about citizenship or lawful work authorization, information that has not traditionally been included as a basic status question on Form 1040. The wording also makes clear that the IRS is not asking whether someone is a U.S. resident for tax purposes. It is asking whether the person falls into one of three categories: a U.S. citizen, a U.S. national, or an alien lawfully authorized to work in the United States.
It’s a bit confusing from a tax perspective because those categories do not line up neatly with the rules governing who must file a federal income tax return.
A nonresident alien, for example, may have a federal income tax filing obligation if they are engaged in a U.S. trade or business, have certain U.S.-source income on which tax was not fully satisfied through withholding, or need to file to claim a refund or tax benefit.
Likewise, a person who is not eligible for a Social Security number may obtain an Individual Taxpayer Identification Number (ITIN) if they have a federal tax purpose for doing so. An ITIN is a tax-processing number. It does not confer immigration status and, by itself, does not authorize someone to work in the United States.
Importantly, someone can have a legitimate federal tax filing obligation without being lawfully authorized to work in the United States.
Timing Matters, Too
The new question also asks about a taxpayer’s status “at the time you file your return.” That’s different from asking about status during the tax year. A taxpayer’s immigration or work-authorization status could change between December 31 and the filing date. For example, a taxpayer may have work authorization for part of the tax year but no longer have it by the time of filing, or may obtain authorization after the year ends but before filing.
Until the IRS releases the 2026 instructions, it remains unclear how the agency intends for taxpayers and preparers to handle those situations. The lack of instructions also leaves practical questions open about what a preparer is expected to know or verify before answering the question, and what consequences, if any, follow from an incorrect response.
Why Is The IRS Asking?
The IRS has not explained why it seeks citizenship and work-authorization information or how it will use it. The timing is likely to attract attention because the IRS has spent much of the past two years at the center of disputes over using taxpayer information for immigration enforcement.
Earlier this year, the IRS shared last-known address information with ICE under a data-sharing arrangement that relied on an exception to the general taxpayer-confidentiality rules in section 6103 of the tax code. The D.C. Circuit later blocked the procedure the IRS had been using, finding that challengers were likely to succeed in showing that the procedure did not comply with the statutory requirements.
That case did not hold that the IRS can never disclose information to ICE. Section 6103 permits disclosures in specified circumstances. But the litigation underscored that information taxpayers provide to the IRS is generally confidential and that the exceptions Congress created are limited.
Schedule 3-A And Refundable Credits
The 2026 draft also changes how it handles certain refundable credits. For 2025, the return simply added the earned income credit, additional child tax credit, refundable American Opportunity Credit, refundable adoption credit, and other refundable amounts on line 32.
For 2026, the draft breaks that calculation into separate steps and adds a new Schedule 3-A, titled Federal Public Benefit. The schedule applies to the refunded portions of the earned income credit, additional child tax credit, refundable American Opportunity Credit, and refundable adoption credit. It asks whether you or your spouse is a U.S. citizen, U.S. national, or a “qualified alien.” If the answer is yes, Schedule 3-A directs the filer to enter zero on Form 1040, line 32b. If the answer is no, the amount determined on the schedule is carried to line 32b and reduces the refundable-credit total on line 32c.
“Qualified alien” is a defined term under federal benefits law, not merely another way of saying someone is legally present or authorized to work in the United States. The category includes lawful permanent residents, refugees, asylees, certain parolees, and several other specifically defined groups.
The schedule follows proposed Treasury regulations issued in August that would treat the refunded portions of those four credits as federal public benefits under the Personal Responsibility and Work Opportunity Reconciliation Act of 1996. Under the proposal, an alien generally would have to be a “qualified alien” on the date the return first claiming the credit is filed in order to receive that refunded portion.
That matters because this language is not identical to the new question on page 1. Form 1040 asks whether the taxpayer or spouse is a citizen, a national, or an alien lawfully authorized to work in the United States. Schedule 3-A, by contrast, uses the term “qualified alien.” These are distinct legal concepts and should not be treated as interchangeable.
The distinction is likely to create confusion if the draft language survives into the final forms, especially because both provisions ask about immigration-related status but use different legal standards. Until the IRS issues final instructions, taxpayers and preparers will need more guidance on how the provisions fit together.
Is There Anything Else?
The draft includes other changes.
Line 12f is new. It reads: “Charitable contribution deduction for non-itemizers.” This reflects a new rule that, beginning in 2026, taxpayers who do not itemize their deductions can claim up to $1,000 in qualifying cash contributions, or $2,000 for joint filers, as a charitable deduction. Because this applies to taxpayers who do not file Schedule A, the deduction now has its own line on Form 1040.
For organizational purposes, this means a reshuffle of lines on Form 1040. In 2025, line 13a was the qualified business income (QBI) deduction, and 13b was the Schedule 1-A deduction. In the 2026 draft, Schedule 1-A moves to line 13a, QBI moves to line 13b, and Schedule 1-A now feeds from line 44 rather than line 38.
Line 24 has been expanded. The 2025 form had a single line 24 for total tax. The 2026 draft now has 24a for the ordinary total, 24b for an amount from Form 1062, and 24c for the combined amount. Form 1062 is new and implements the section 1062 election, which allows tax attributable to certain sales or exchanges of qualified farmland property to qualified farmers to be paid in four annual installments.
Finally, there are the expected annual updates, including an increase in the standard deduction amounts from $15,750 for single taxpayers, $31,500 for married taxpayers filing jointly, and $23,625 for heads of households in 2025 to $16,100 for single taxpayers, $32,200 for married taxpayers filing jointly, and $24,150 for heads of households in 2026. The footer on Form 1040 now also includes a brief promo for Free File, the federal program that lets eligible taxpayers prepare and file their returns online for free.
What Happens Next?
As always, don’t hit print just yet. The IRS warns:
This is an early release draft of an IRS tax form, instructions, or publication, which the IRS is
providing for your information. Do not file draft forms. (emphasis added)
The IRS goes on to say:
However, unexpected issues occasionally arise, or legislation is passed—in this case, we will post a
new draft of the form to alert users that changes were made to the previously posted draft. Thus, there
are never any changes to the last posted draft of the form and the final revision of the form. Forms and
instructions are subject to OMB approval before they can be officially released, so we post drafts of
them until they are approved. Drafts of instructions and publications usually have some additional
changes before their final release…
(As most practitioners are aware, forms and instructions can and do change, even after publication. Last year, the IRS released a January 30, 2026, edition of the Form 1040 instructions. On February 25, 2026—about a month after the tax season began—the IRS updated the Form 1040 instructions to make clear that the tips deduction is further limited by subtracting all deductions allocable to the trade or business.)
For now, you can submit comments to the IRS about this draft or others at IRS.gov/FormsComments. Include “NTF” followed by the form or publication number (here, “NTF1040”) in the body of the message. The IRS notes that it cannot respond to all comments due to the high volume it receives and “may not be able to consider many suggestions until the subsequent revision of the product,” but says it will review each “NTF” message.